Fractional CFO & Advisory
Strategic forecasting and finance leadership for stronger decisions.
Explore service
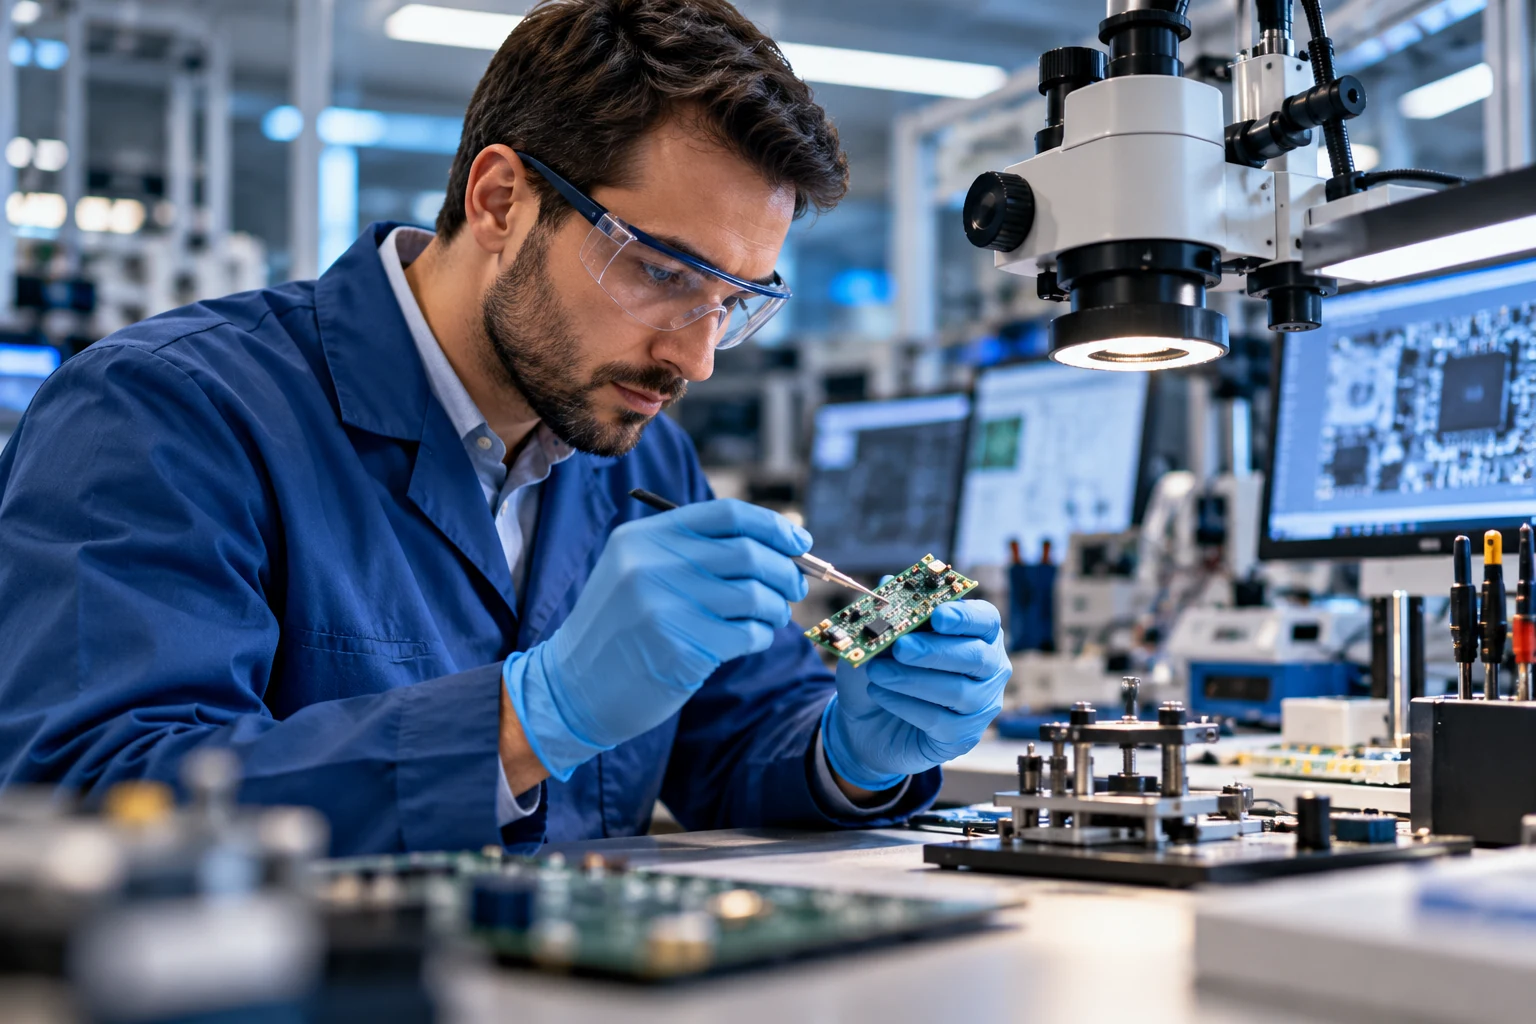
Canada’s Scientific Research and Experimental Development (SR&ED) tax incentive program may provide tax benefits for eligible work. A strong submission begins with understanding the technological challenges, experimental activities and supporting records—not simply labelling all product development as research.
Discuss the scientific or technological uncertainty involved and whether the work was conducted through systematic experimentation or analysis.
Help organize the description of the objectives, uncertainties, work performed and advancements sought in a clear, evidence-based format.
Identify records relevant to potentially allowable SR&ED costs, including supporting financial documentation and employee time records.
Help align technical and financial material required for a claim and consider how CRA forms and review requirements apply.
No. Eligibility depends on whether the work meets the CRA criteria for scientific or technological advancement and systematic investigation or search.
No. Entitlement, eligible expenditures and any refundability depend on the specific facts and applicable law, and claims may be reviewed by CRA.
Dated project records, experiments, testing results, design documents, source code history, time records and expenditure records may all be relevant depending on the work.
Every business has different systems, deadlines and priorities. Contact us to discuss your needs and confirm which services are appropriate for your situation.
Request a Consultation ↗Strategic forecasting and finance leadership for stronger decisions.
Explore service
Corporate tax, GST/HST coordination and thoughtful Canadian tax support.
Explore service
Reliable monthly bookkeeping and reconciliations for clearer business decisions.
Explore service